
 See My Latest Article on HelloNation
What Does Homeowners Insurance Cover?
Homeowners insurance typically provides financial protection for your home and belongings against sudden events like fire, theft, or certain natural disasters—not regular wear and tear. For most properties in Shelton, standard policies include:
- Dwelling coverage: Repairs or rebuilds your house structure if it’s damaged by covered hazards, such as lightning, wind, or accidental fire.
- Personal property: Covers furniture, clothing, electronics, and other belongings if stolen or damaged inside or outside your home (policy limits apply).
- Liability protection: Helps with legal costs or medical bills if someone is injured on your property.
- Additional living expenses: Pays for temporary housing if your home is unlivable due to a covered claim, which can be a relief when local repairs take time.
However, there are exclusions. Flooding and earthquakes, for example, are typically not included and require separate policies. In the Shelton area, flooding from heavy rains or melting snow in spring can surprise those unfamiliar with their policy’s limits.
How Are Homeowners Insurance Rates Determined?
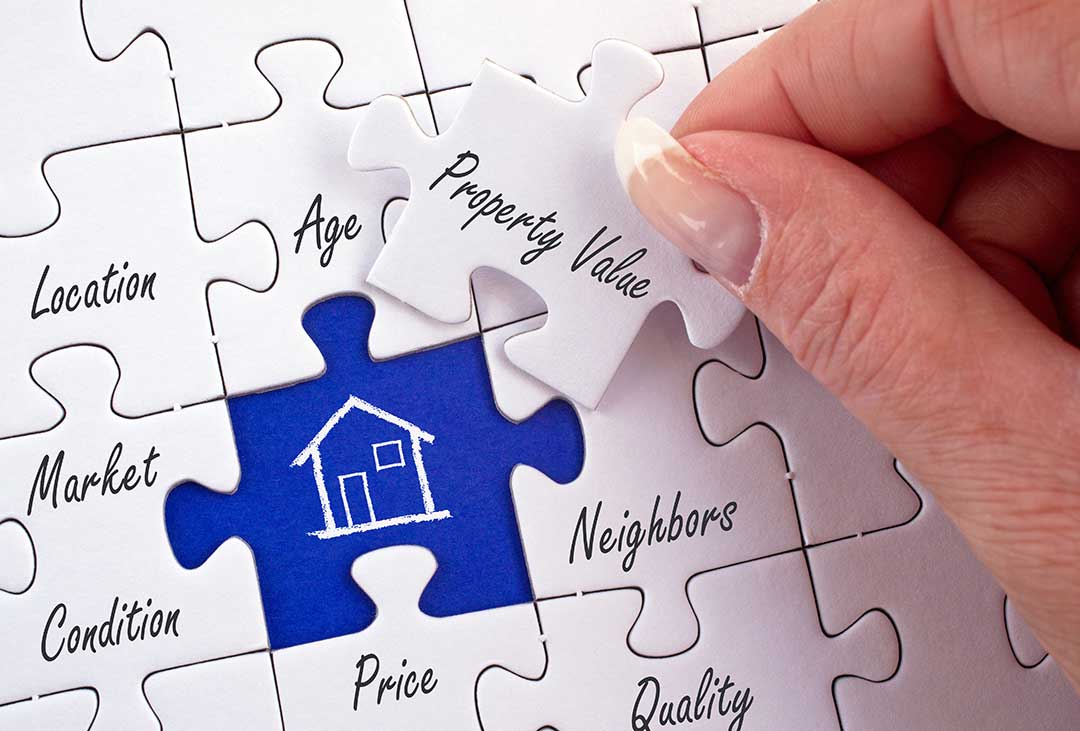
Insurers look at a variety of factors to set rates for local households, including the age and condition of your home, construction materials, and its size. The location within Shelton is important: proximity to rivers, wooded areas, and fire hydrants will affect your premium, as does the historical weather in the region.
Personal claims history and even your credit can factor in. Homes with recent updates to plumbing, roofing, or wiring could qualify for lower rates. Meanwhile, older homes with outdated electrical systems or roof issues may see higher costs.
Does Insurance Replace Or Repair Everything?
Not always. Insurance covers sudden, accidental damage from specific perils listed in your policy—like a kitchen fire or burglary—not gradual problems like mold, termites, or long-term leaks. For example:
- A burst pipe on a cold winter night could be covered, especially if you’ve taken reasonable steps to prevent freezing.
- Slow, unnoticed leaks that let water damage accumulate over months are often excluded.
- Storm wind damage to a roof may be covered, but gradual shingle wear usually is not.
Limits, caps, and deductibles also apply. Area homeowners should check personal property limits for jewelry, art, or collectibles, as these may require separate riders for full protection.
What Are Common Misconceptions?
Many residents believe all home disasters are covered. In truth, policies typically exclude:
- Flood damage (including overflow from local streams after heavy rain or snowmelt)
- Sewer backups
- Damage from neglect, lack of maintenance, or pest infestations
Small details can be costly to overlook. For instance, not all accidental water damage is treated the same—water entering from the ground up (as during flooding) won’t be covered by standard insurance, regardless of the intensity of the weather.
Are There Local Hazards to Consider?
Shelton experiences four seasons, bringing unique risks:
- Winter: Heavy snows and ice dams can lead to frozen pipes and roof leaks. Insurers may look for evidence of proper insulation or roof maintenance.
- Spring: Rapid snowmelt and rain can cause basement flooding, so some homeowners may want to ask about flood insurance, even if not in a high-risk area.
- Summer storms: Wind and hail damage is covered under most policies, but fallen trees that don’t cause home damage may not trigger a claim.
- Fall: Wet leaves and clogged gutters can contribute to water backup claims—a situation often misunderstood in terms of coverage.
How Should Local Residents Review Their Coverage?
Start by gathering your policy paperwork and reading the declarations page, where main coverages and limits are listed. Consider:
- Updating your home inventory after renovations, new purchases, or significant life changes.
- Checking special limits for valuables or outbuildings, which may not be automatically covered.
- Reviewing exclusions and clarifying questions with your insurer for scenarios like detached garages, new sheds, or rental situations.
Keeping documentation—such as receipts, photos, and a log of home upgrades—makes claims run more smoothly.
What About Flood and Natural Disaster Policies?
Standard homeowners policies won’t pay for flood damage from storms, rising water tables, or snowmelt. Flood insurance is offered as a separate product, often through the National Flood Insurance Program (NFIP). While only some local properties are in official flood zones, even outside those areas, flash flooding can happen—especially near rivers, wetland zones, and low-lying neighborhoods.
Earthquake coverage is rarely purchased in the area, but it’s available. Compare deductible and cost with your risk tolerance, keeping in mind earthquakes are very rare locally.
What Happens During a Claim?
If you suffer a loss, notify your insurer promptly with as much detail and documentation as you can provide. Claims are typically processed with a visit from an adjuster, who will inspect the damage and estimate repair costs. Keeping records—photos of your property before and after, receipts for temporary repairs, and police reports for thefts—can speed up and strengthen your case.
Most policies have deductible amounts, so only losses above that amount will be reimbursed. Pay attention to coverage limits for replacement cost versus actual cash value, as depreciation can impact your payout.
How Can Insurance Be Kept Affordable?
There are several ways local households may keep premiums manageable:
- Increasing the deductible (the amount paid out of pocket before insurance kicks in)
- Bundling home and auto policies, if worthwhile in your situation
- Upgrading safety features—like smoke detectors, burglar alarms, or sump pumps—to reduce risk
- Performing regular maintenance, since insurers may deny claims for preventable damage caused by neglect
Each situation is different, so compare costs, and reassess your policy after major home changes.